Everything you need to know about financing a Can-Am Defender Financing Options, from credit requirements to monthly payment estimates.
So you’ve fallen for the Can-Am Defender and honestly, who wouldn’t? It’s one of the toughest side-by-sides on the market, built to haul, tow, and work as hard as you do. But before you can park one in your driveway, there’s the big question: how do you actually pay for it?
The good news is that Can-Am Defender financing options have never been more flexible. Whether you’re a rancher who needs a workhorse, a weekend trail rider, or a small business owner adding a utility vehicle to your fleet, there’s a financing path that fits your budget. This guide breaks down every option available in 2026, walks you through the application process, and answers the questions real buyers are asking right now.
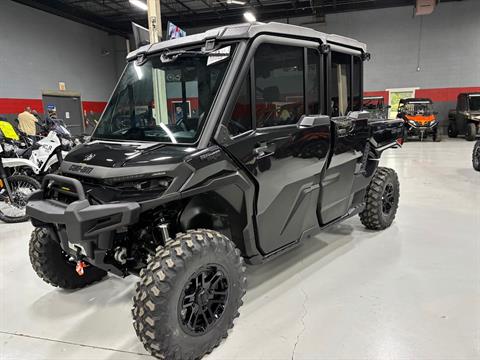
Table of Contents
- AI Overview: Quick Answers About Can-Am Defender Financing
- Why Financing a Can-Am Defender Makes Sense
- Can-Am Defender Financing Options Explained
- What Affects Your Can-Am Defender Loan Rate
- How Much Does It Cost to Finance a Can-Am Defender?
- Step-by-Step: How to Apply for Can-Am Defender Financing
- Tips to Get Approved With the Best Rate
- Leasing vs. Financing a Can-Am Defender
- Frequently Asked Questions
- Final Thoughts and Next Steps
Quick Answers About Can-Am Defender Financing
What are the main Can-Am Defender financing options? A: Buyers can choose between BRP dealer financing, bank or credit union loans, online powersports lenders, and in-house dealer financing programs. Each offers different rates, terms, and approval requirements.Can-Am Defender Financing Options
What credit score do I need to finance a Can-Am Defender? A: Most lenders prefer a credit score of 650 or higher for the best rates, though some dealer and in-house programs accept scores as low as 550–600 with a larger down payment.Can-Am Defender Financing Options
How much is a monthly payment on a Can-Am Defender? A: Depending on the model, down payment, and loan term, monthly payments typically range from $250 to $600 for a 36–72 month loan.
Can I finance a Can-Am Defender with no credit history? A: Yes. Some dealers offer first-time buyer or co-signer programs specifically for riders with limited or no credit history.
Why Financing a Can-Am Defender Makes Sense
A brand-new Can-Am Defender can run anywhere from $14,000 for a base HD7 model to well over $30,000 for a fully loaded Limited or X mr trim. That’s a significant chunk of cash to pay upfront, which is exactly why Can-Am Defender financing exists to spread that cost into manageable monthly payments while you start using the vehicle right away.Can-Am Defender Financing Options
Financing also gives you room to:
- Preserve your cash flow for other business or personal expenses
- Choose add-ons like winches, plows, or cabs without draining your savings
- Build credit history through consistent on-time payments
- Take advantage of seasonal promotional APR offers from BRP and dealers
If you’re comparing your options for a work-ready UTV, it’s worth browsing our current Can-Am Defender for sale inventory before locking in a loan amount, since the trim and price you choose directly affect your financing terms.
Can-Am Defender Financing Options Explained
There isn’t a single “best” way to finance a Can-Am Defender the right choice depends on your credit profile, how quickly you need approval, and whether you want promotional financing perks. Here’s a breakdown of the four most common Defender financing options.
Dealer Financing Through BRP
BRP (the manufacturer behind Can-Am) regularly partners with financial institutions to offer promotional financing directly through authorized dealers. These offers often include:
- 0% APR for qualified buyers during promotional periods
- Low monthly payment structures for 36–72 month terms
- Bundled financing for accessories purchased at the same time
This is usually the fastest route since the paperwork happens right at the dealership. If you’re shopping now, check our Can-Am Defender for sale listings to see which models qualify for manufacturer promotions this month.
Bank and Credit Union Loans
If you already have a relationship with a bank or credit union, a personal or recreational vehicle loan can be a smart alternative. Benefits include:
- Potentially lower interest rates for members with strong credit
- More flexible repayment terms
- The ability to shop with pre-approved financing in hand, giving you negotiating leverage at the dealer
The tradeoff is a slower approval process compared to dealer financing, since banks typically require more documentation.
Online Powersports Lenders
A growing number of online lenders specialize in powersports and UTV financing. These platforms let you:
- Get pre-qualified in minutes with a soft credit check
- Compare multiple loan offers side by side
- Finance both new and used Can-Am Defenders
This option works well for buyers who want to compare rates before stepping into a dealership.
In-House Dealer Financing
For buyers with lower credit scores, some dealers offer in-house financing (sometimes called “buy here, pay here”). While approval is easier, interest rates tend to run higher. This route makes sense as a last resort or a stepping stone toward better financing on a future purchase, such as an upgrade covered in our Can-Am Defender vs. Defender Max comparison.Can-Am Defender Financing Options
What Affects Your Can-Am Defender Loan Rate
Several factors determine the interest rate and terms you’ll be offered:
Credit Score
Higher scores unlock lower APRs. A 700+ score often qualifies for promotional or near-promotional rates.
Down Payment
A larger down payment reduces the loan principal, lowers your monthly payment, and can improve your approval odds.
Loan Term Length
Shorter terms (36 months) mean higher monthly payments but less interest paid overall. Longer terms (72–84 months) lower your monthly payment but increase total interest.
New vs. Used Defender
New models typically qualify for better promotional rates than used units, though used Can-Am Defender for sale financing is still widely available and often comes with a lower purchase price to finance overall.
Debt-to-Income Ratio
Lenders look at your existing monthly obligations relative to income to gauge repayment ability.
How Much Does It Cost to Finance a Can-Am Defender?
Here’s a simplified look at what monthly payments might look like based on loan amount, term, and an estimated APR (actual rates vary by lender and credit profile):
| Defender Price | Down Payment | Loan Term | Estimated APR | Approx. Monthly Payment |
|---|---|---|---|---|
| $16,000 | $2,000 | 60 months | 7.9% | ~$284 |
| $22,000 | $3,000 | 60 months | 7.9% | ~$385 |
| $28,000 | $4,000 | 72 months | 8.9% | ~$430 |
| $33,000 | $5,000 | 72 months | 8.9% | ~$500 |
These figures are estimates for illustration only. Always request a personalized quote before signing.
Step-by-Step: How to Apply for Can-Am Defender Financing
- Check your credit score — Know where you stand before applying so you can target the right lenders.
- Decide on a budget — Factor in insurance, maintenance, and accessories, not just the loan payment.
- Get pre-qualified — Use an online lender or your bank to see estimated rates with a soft credit pull.
- Compare offers — Weigh dealer promotions against outside loan pre-approvals.
- Visit the dealer — Bring proof of income, ID, and your pre-approval letter if you have one.
- Finalize the paperwork — Review the APR, term length, and any add-on protection plans carefully before signing.
- Drive away — Once approved, your Defender financing is locked in and you’re ready to ride.
For a deeper walkthrough of paperwork requirements, see our step-by-step UTV loan application checklist.
Tips to Get Approved With the Best Rate
- Pay down existing debt before applying to improve your debt-to-income ratio.
- Save for a bigger down payment — even an extra $1,000–$2,000 can meaningfully lower your rate.
- Avoid multiple hard credit pulls in a short window; use soft-check pre-qualification tools first.
- Time your purchase around seasonal promotions, which often appear in spring and late fall.
- Bundle smart — financing accessories with the vehicle can sometimes qualify for the same promotional rate.
Leasing vs. Financing a Can-Am Defender
While financing is the most common route, some commercial buyers ask about leasing. Here’s a quick comparison:
| Factor | Financing | Leasing |
|---|---|---|
| Ownership | You own it after final payment | You return or buy out at lease end |
| Monthly Payment | Higher | Typically lower |
| Customization | Unlimited | Often restricted |
| Best For | Long-term owners | Businesses upgrading equipment frequently |
For most personal buyers, financing remains the better long-term value, especially if you plan to keep the vehicle for years and eventually explore Can-Am Defender upgrades and accessories.
Frequently Asked Questions
Can I finance a used Can-Am Defender? Yes. Most banks, credit unions, and online powersports lenders offer used UTV financing, though rates may be slightly higher than new-model promotions. Browse our current Can-Am Defender for sale inventory to compare used pricing before applying.
Is 0% APR financing really available on the Can-Am Defender? Yes, BRP periodically offers 0% APR promotions on select models for well-qualified buyers, usually during specific sales events. Availability varies by region and season.
What’s the minimum down payment for Can-Am Defender financing? This varies by lender, but many require at least 10% down. Some in-house dealer programs may accept less with a higher interest rate.
Can I get financing with bad credit? Yes, though options are more limited and rates are higher. In-house dealer financing or a co-signer can improve approval chances.
How long are typical Can-Am Defender loan terms? Loan terms usually range from 36 to 84 months, depending on the lender and loan amount.
Does financing include the cost of accessories? Some dealer financing packages allow you to roll accessory costs into the total loan amount, subject to lender approval.
Final Thoughts and Next Steps
Financing a Can-Am Defender doesn’t have to be complicated. Once you understand the main Can-Am Defender financing options dealer financing, bank loans, online lenders, and in-house programs you can confidently compare rates and pick the path that fits your budget and credit profile.
Ready to see what you qualify for? Get pre-qualified for Can-Am Defender financing today and take the next step toward owning the UTV that works as hard as you do. You can also browse our full Can-Am Defender for sale inventory to find the trim and price point that matches your financing plan.