The good news is that you do not have to pay cash. Polaris Ranger financing options are more flexible than ever, and there is a path for nearly every budget and credit profile. In this guide, we walk through every realistic way to pay for a Ranger, what lenders look for, how to compare offers, and how to avoid the mistakes that cost buyers thousands. Whether you are shopping for a brand new model or a gently used one, you will leave with a clear plan.
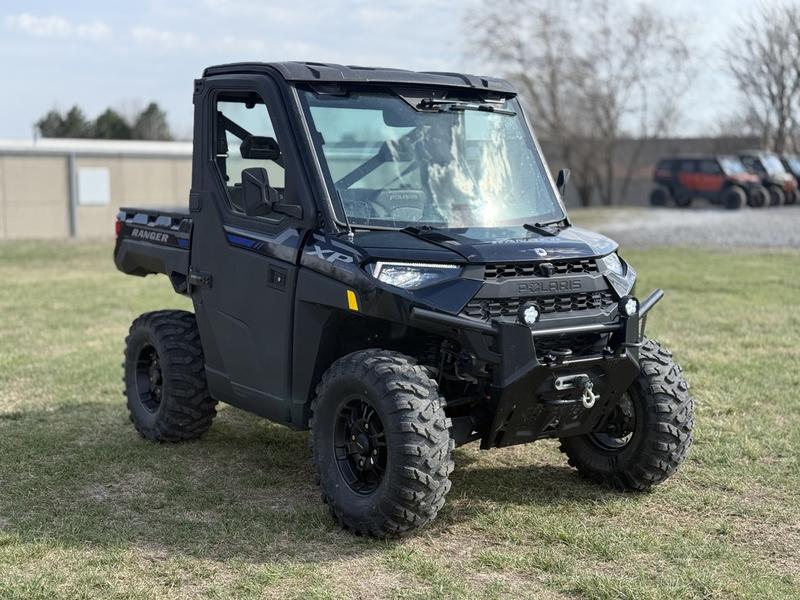
Table of Contents
- Quick Answers: Polaris Ranger Financing at a Glance
- Why Financing a Polaris Ranger Makes Sense
- Polaris Ranger Financing Options Compared (Table)
- The Main Ways to Finance a Polaris Ranger
- What Lenders Look at Before Approving You
- New vs. Used Polaris Ranger Financing
- Step-by-Step: How to Get Approved
- Costly Financing Mistakes to Avoid
- Smart Ways to Lower Your Monthly Payment
- Final Thoughts and Next Steps
- Frequently Asked Questions (FAQs)
Quick Answers: Polaris Ranger Financing at a Glance
This section gives short, direct answers to the questions buyers ask most often.
What are the best Polaris Ranger financing options?
The most common options are dealer financing, credit union loans, bank loans, personal loans, manufacturer promotional financing (usually on new units) and lease-style or rent-to-own programs. Credit unions and banks often offer competitive rates on used machines, while dealer financing is the most convenient.
Can I finance a used Polaris Ranger?
Yes. Many lenders finance used UTVs, though terms may be shorter and rates slightly higher than for new models. A well-maintained used Ranger with documented history is easier to finance than a high-hour machine with unknown service records.
What credit score do I need?
There is no single cutoff. Buyers with good to excellent credit typically see the best rates, but lenders also consider income, down payment and debt load. Some lenders work with fair or rebuilding credit, usually at a higher rate.
How much should I put down?
Many buyers aim for 10 to 20 percent of the purchase price. A larger down payment can improve approval odds and reduce your monthly payment and total interest.
How long are typical loan terms?
Terms commonly range from about 24 to 72 months, depending on the lender, the vehicle’s age and price, and your credit. Longer terms lower the payment but increase the total interest you pay.
Note: Rates, terms and approval standards change often and vary by lender, so always confirm current numbers directly with the lender before you sign.
Why Financing a Polaris Ranger Makes Sense
A Polaris Ranger is not a toy. For many owners it replaces a truck on the property, hauls feed and firewood, plows snow, and carries the family to the deer stand. Because it is a working asset, spreading the cost over time often makes more financial sense than draining savings.
Keep Your Cash Available
Financing lets you hold on to your emergency fund or business capital. If you run a farm, landscaping crew or hunting lodge, that cash flexibility can matter more than saving a few dollars in interest.
Build Credit With Steady Payments
An installment loan paid on time can strengthen your credit history. That helps the next time you apply for a mortgage, a truck loan or a business line of credit.
Get the Right Machine Now, Not Later
Waiting years to save the full price may mean missing a great deal on the exact model you want. Financing helps you buy when the right Ranger shows up, especially when inventory is limited.
Polaris Ranger Financing Options Compared
Use this table as a quick reference before you dive into the details.
| Financing Option | Best For | Typical Pros | Typical Cons |
|---|---|---|---|
| Dealer financing | Convenience and one-stop buying | Fast approval, multiple lenders, easy paperwork | Rates can vary; read the fine print |
| Credit union loan | Used and new Rangers | Often lower rates, member-friendly terms | Membership required, slower process |
| Bank loan | Existing bank customers | Familiar process, relationship perks | Stricter approval for older units |
| Personal loan | Older or lower-priced used Rangers | No collateral on some loans, flexible use | Rates may be higher than secured loans |
| Manufacturer promotions | New Rangers | Occasional low-rate or special offers | Usually limited to new models and qualified buyers |
| Bad credit or subprime lending | Rebuilding credit | Higher approval chance | Higher rates, larger down payment |
| Home equity loan or HELOC | Homeowners with equity | Lower rates | Your home secures the debt |
The Main Ways to Finance a Polaris Ranger
Every buyer’s situation is different. Here is a closer look at each path, with the strengths and trade-offs that matter most.
Dealer Financing
Dealer financing is the path most people take because it is simple. You pick your machine, fill out one application, and the dealer shares it with its network of lenders.
How Dealer Financing Works
The dealer submits your application to one or more lenders, who respond with offers. You choose the one that fits, sign the paperwork and drive home, often the same day.
Pros and Cons of Dealer Financing
The biggest advantages are speed and convenience. The trade-off is that you should still compare the offer against an outside quote, because the rate you are shown may not be the lowest available to you.
If you are browsing inventory, you can see what is available on our Polaris Ranger UTV for sale page and then talk with our team about payment options that fit the model you like.
Credit Union Loans
Credit unions are member-owned, and they frequently offer some of the most competitive rates on powersports and recreational vehicle loans.
Why Credit Unions Often Win on Rate
Because they are not-for-profit, credit unions often pass savings to members through lower rates and fewer fees. They can also be more flexible with borderline applicants who have a solid relationship with the institution.
What to Watch For
You must become a member, and the process can take a little longer than dealer financing. Get pre-approved before you shop so you can negotiate with confidence.
Bank Loans
If you already bank with a large or community bank, ask about a recreational vehicle or powersports loan. Existing customers sometimes receive rate discounts for autopay or bundled accounts.
Secured vs. Unsecured Bank Loans
Most UTV loans are secured, meaning the Ranger is the collateral. Unsecured personal loans exist but usually carry higher rates because the lender has nothing to repossess if you default.
Manufacturer Promotional Financing
Polaris and its financing partners periodically run special offers on new models, such as reduced interest rates or promotional terms. These deals change frequently and generally require strong credit.
Are Promotions Always the Best Deal?
Not necessarily. A low promotional rate can come with a higher sticker price or fewer negotiating options. Compare the total cost of the loan, not just the monthly payment or the headline rate.
Bad Credit and Subprime UTV Financing
A low credit score does not automatically end your search. Some lenders specialize in helping buyers who are rebuilding credit.
What to Expect
Expect a higher interest rate, a larger down payment and possibly a shorter term. The upside is that making consistent payments can improve your score, and you may be able to refinance later at a better rate.
How to Improve Your Chances
Bring proof of steady income, offer a bigger down payment, consider a co-signer, and choose a more affordable used Ranger instead of stretching for a newer one.
Home Equity Options
Homeowners sometimes use a home equity loan or line of credit for lower interest. This can reduce your rate, but it puts your home at risk if you fall behind. Many buyers prefer to keep recreational purchases separate from their home.
What Lenders Look at Before Approving You
Understanding how lenders evaluate your application helps you prepare and improve your odds.
Credit Score and History
Your credit score shows how reliably you have repaid debt. Higher scores generally unlock lower rates. Lenders also look at late payments, collections and recent applications.
Income and Employment Stability
Lenders want to see that you can comfortably afford the payment. Recent pay stubs, tax returns or bank statements help, and self-employed buyers should be ready with additional documentation.
Debt-to-Income Ratio
This ratio compares your monthly debt payments to your monthly income. A lower ratio signals that you can handle another payment without strain.
Down Payment
A meaningful down payment reduces the lender’s risk. It also lowers the amount you borrow, which means less interest over the life of the loan.
Age, Condition and Value of the Ranger
For used machines, the model year, hours, mileage and overall condition matter. Lenders want collateral that holds value, which is one reason a clean, well-documented Ranger is easier to finance.
New vs. Used Polaris Ranger Financing
One of the biggest decisions you will make is whether to buy new or used. Each route changes your financing picture.
Financing a New Polaris Ranger
New models may qualify for promotional rates and longer terms. The trade-off is faster depreciation in the first couple of years and a higher amount financed, which raises your payment and insurance costs.
Financing a Used Polaris Ranger
Used financing is where many smart buyers find the best value. You pay less up front, avoid the steepest depreciation and often finance a smaller balance. Rates may be a bit higher than promotional new-model offers, but the lower loan amount can still mean a lower payment overall.
Tips for Financing a Used Ranger
- Ask for service records and confirm the VIN before you apply.
- Have the machine inspected, especially the drivetrain, suspension and engine hours.
- Get pre-approved so you know your budget before you fall in love with a specific unit.
- Compare at least two or three lenders.
Ready to compare options? Browse our full used utility vehicles shop to see Rangers and other work-ready machines that may fit your budget.
Step-by-Step: How to Get Approved for Polaris Ranger Financing
Follow this simple roadmap to move from browsing to buying with confidence.
Step 1: Check Your Credit
Review your credit report for errors and know your score before you apply. Correcting mistakes early can save you real money.
Step 2: Set a Realistic Budget
Decide what monthly payment fits comfortably. Remember to include insurance, fuel, maintenance, accessories and registration, not just the loan payment.
Step 3: Save a Down Payment
Aim for a solid down payment if you can. Even a modest amount helps, and trade-in equity from an old UTV or ATV can count toward it.
Step 4: Get Pre-Approved
Apply with a credit union or bank first. Pre-approval gives you a benchmark rate and stronger negotiating power at the dealership.
Step 5: Compare Offers
Look at the annual percentage rate (APR), term length, fees, prepayment penalties and total cost. The lowest payment is not always the cheapest loan.
Step 6: Choose Your Ranger and Finalize
Pick the model that matches your needs, whether that is a crew cab for family trips or a utility-focused model for hauling. Review every document before you sign.
Costly Financing Mistakes to Avoid
A few common missteps can turn a good deal into an expensive one.
Focusing Only on the Monthly Payment
Stretching the term to hit a low payment can cost you thousands more in interest. Always ask for the total amount you will pay over the life of the loan.
Skipping Pre-Approval
Walking in without a competing offer gives you less leverage. A pre-approval letter shows you are a serious buyer and keeps the dealer honest.
Ignoring Fees and Add-Ons
Ask about origination fees, documentation fees, extended warranties and optional protection plans. Some are valuable, but you should choose them, not have them bundled by default.
Buying More Machine Than You Need
It is easy to get swept up in features. Match the Ranger to your real use. A reliable older model that does the job is often smarter than a loaded unit that strains your budget.
Applying to Too Many Lenders at Random
Shopping for rates is smart, but spreading applications across many weeks can hurt your credit. Try to submit your applications within a short window so they are treated as a single shopping event.
Smart Ways to Lower Your Monthly Payment
You have more control over your payment than you might think.
Increase Your Down Payment or Trade-In Value
Every dollar you put down is a dollar you do not finance. Trading in an older vehicle can make a real difference.
Choose a Slightly Older Model
A well-kept used Ranger often delivers nearly the same capability for far less money. That lowers both the loan balance and your insurance cost.
Improve Your Credit Before Applying
Pay down credit card balances, avoid new debt and make every payment on time for a few months. Even a modest score increase can lead to a better rate.
Consider Refinancing Later
If your credit improves or rates drop, refinancing can reduce your payment or shorten your term. Check that your loan has no penalty for early payoff.
Final Thoughts and Next Steps
Financing a Polaris Ranger does not have to be confusing. Start by knowing your credit, setting a budget you can live with and getting pre-approved. Compare dealer financing against credit unions and banks, weigh new against used, and always look at the total cost, not just the monthly number.
When you are ready to find your machine, explore our current selection of Polaris Ranger UTVs for sale or browse the complete used utility vehicle inventory. Have questions about financing a specific unit? Contact our team today and let us help you find the right Ranger at a payment that works for you.
Frequently Asked Questions (FAQs)
Does Polaris offer its own financing?
Polaris has historically partnered with financing providers to offer promotional programs, mostly on new models. Availability and terms change, so check current offers and ask the dealer which programs apply.
Can I get Polaris Ranger financing with bad credit?
Yes, it is often possible. Expect a higher rate and a larger down payment, and consider a co-signer. On-time payments can help you rebuild credit and refinance later.
Is it better to finance through a dealer or a credit union?
It depends. Dealers offer convenience and multiple lender options, while credit unions often provide lower rates. The best strategy is to get a credit union pre-approval and then see whether the dealer can beat it.
How long can I finance a used Polaris Ranger?
Terms vary with the vehicle’s age, price and your credit. Older or lower-priced machines usually get shorter terms, while newer units may qualify for longer ones.
Is there a minimum down payment?
Some lenders approve with little or nothing down for strong credit, but many prefer 10 to 20 percent. A larger down payment typically improves your terms.
Can I pay off my Ranger loan early?
In most cases yes, and doing so can save interest. Confirm there is no prepayment penalty before signing.
Does financing cover accessories like a winch or roof?
Sometimes. Some lenders allow accessories to be rolled into the loan, but that increases the amount financed. Ask about this up front.
What documents do I need to apply?
Typically a valid ID, proof of income, proof of residence and details about the vehicle. Self-employed buyers may need tax returns or bank statements.
Will applying for financing hurt my credit score?
A lender’s credit check may cause a small, temporary dip. Submitting several applications within a short window is generally treated as one inquiry for auto-style loans, but confirm with your lender.
What else should I budget for besides the loan payment?
Plan for insurance, registration, fuel, maintenance, tires, accessories and safety gear. These costs add up, so include them when deciding how much Ranger you can afford.