A used utility vehicle (UTV) whether for farming, landscaping, construction, or hunting can be a game-changer for your business or lifestyle. But upfront costs for a reliable second-hand model can strain your budget.
That’s where used utility vehicle financing comes in. Lenders now offer specialized loans for pre-owned Polaris Rangers, John Deere Gators, Can-Am Defenders, and Kubota RTVs. In this guide, we’ll break down how used UTV financing works, who qualifies, and answer your most frequently asked questions.
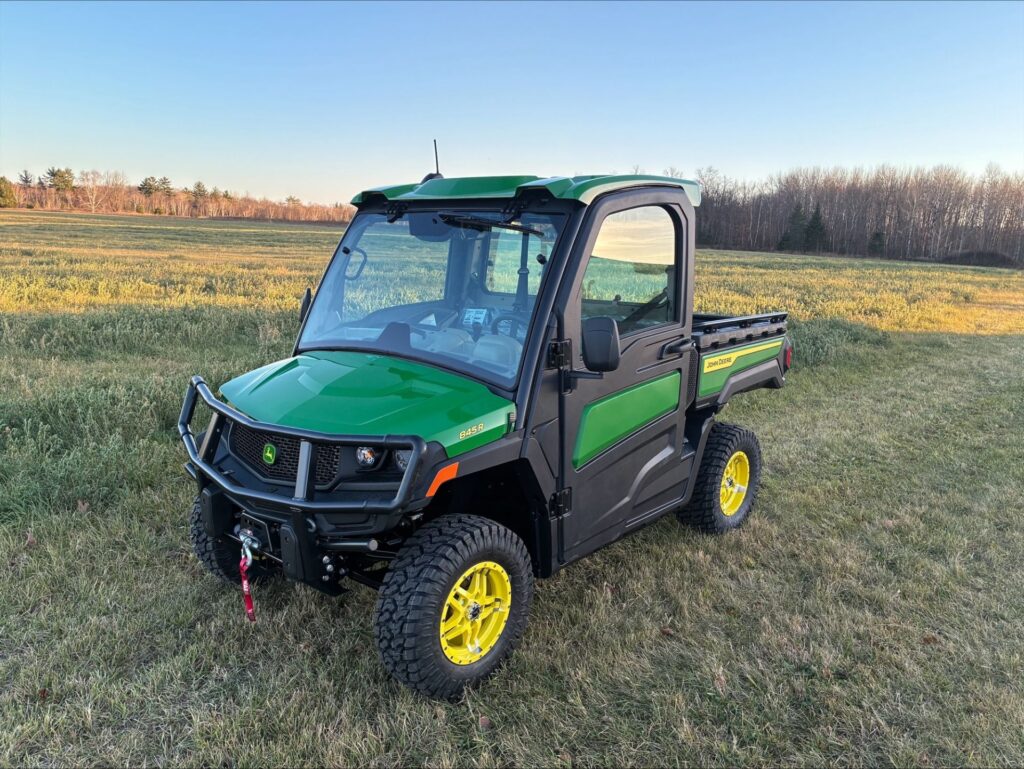
Why Finance a Used Utility Vehicle?
Before diving into the how, here’s why financing a used UTV is a smart move:
- Lower monthly payments : Preserve cash flow for maintenance or other gear.
- Build business credit : Many lenders report to commercial credit bureaus.
- Access higher-quality models : A financed $15k used UTV often outperforms a $5k cash junker.
- Tax advantages : Section 179 deductions may apply for business-use UTVs (consult your CPA).
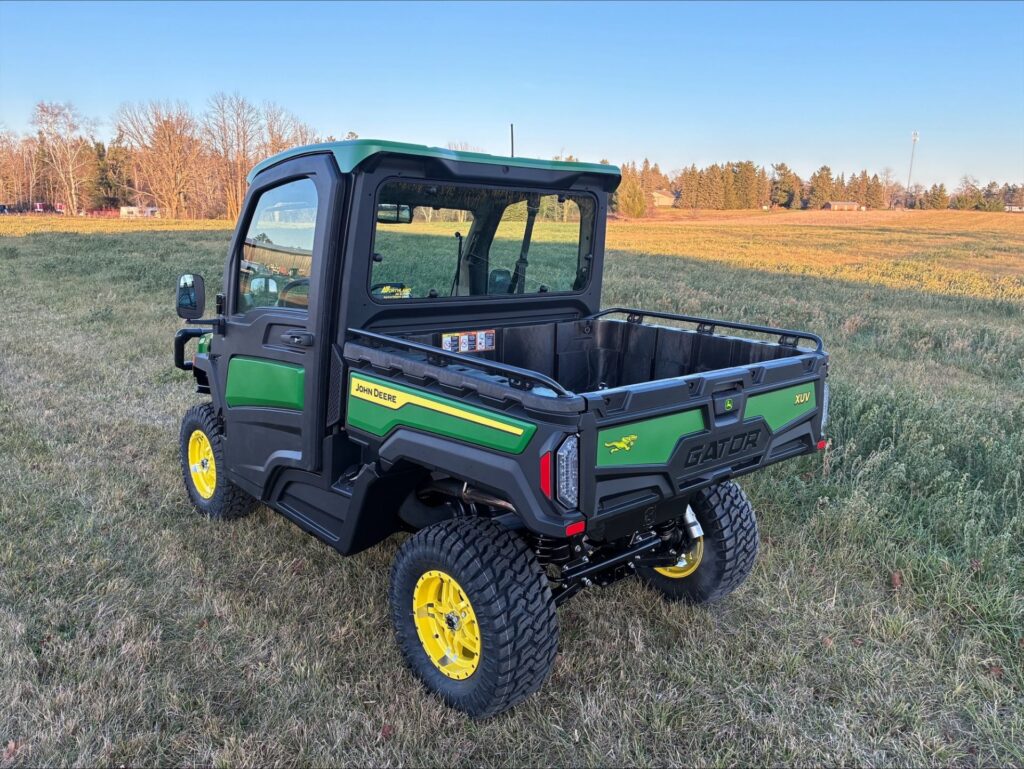
3 Things Lenders Check for Used UTV Financing
When you apply for financing on a used utility vehicle, lenders focus on:
- Vehicle age & mileage : Most lenders limit to models 10 years old or newer with under 5,000 hours/miles.
- Your credit score : 650+ gets best rates; 550–650 may still qualify with larger down payments.
- Purpose of use : Commercial (farming/contracting) vs. personal (recreation/hunting).
Have a bill of sale or dealer quote ready. Private-party used UTV purchases are harder to finance than dealer-sold units.
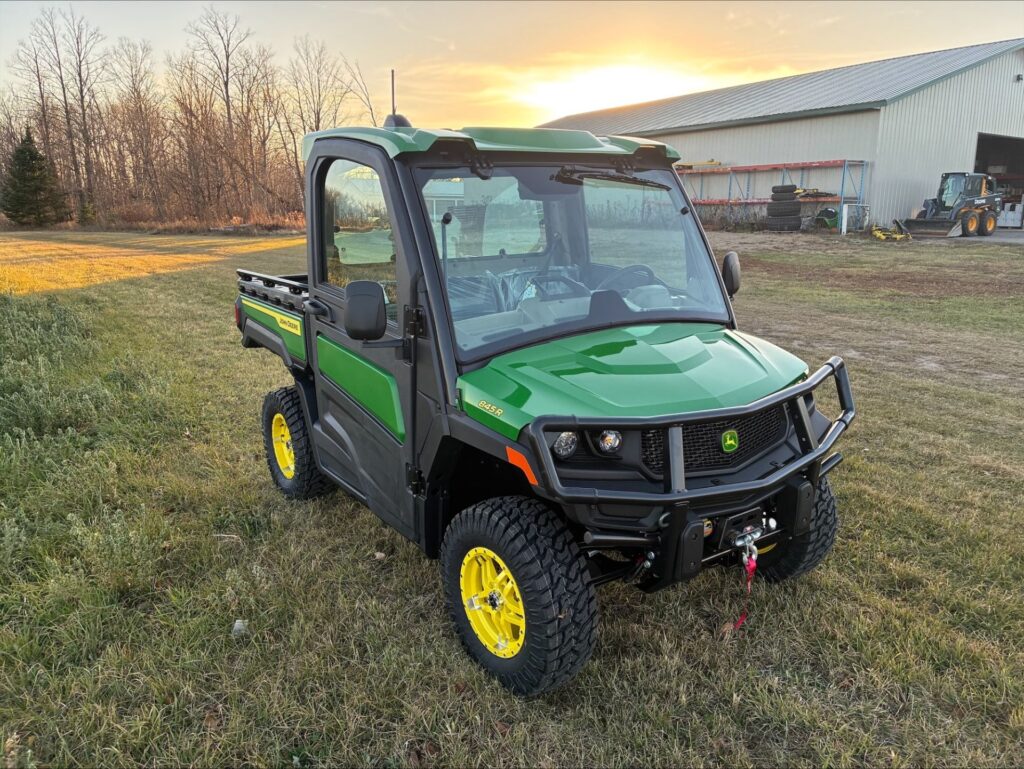
How to Get the Best Used UTV Loan Rates
Follow these steps to secure affordable used utility vehicle financing:
- Improve your credit – Pay down revolving debt before applying.
- Save for 10–20% down – Lowers risk and interest rates.
- Compare 3+ lenders – Don’t just use dealer financing. Try credit unions, agricultural lenders, and online equipment financiers.
- Choose shorter terms – 24–48 months typically beat 60–72 month rates.
Current average APRs for used UTV loans (as of 2026):
- Excellent credit (720+): 6% – 10%
- Good credit (650–719): 10% – 15%
- Fair credit (550–649): 15% – 24%
Frequently Asked Questions (FAQ) About Used Utility Vehicle Financing
1. Can I finance a used UTV from a private seller?
Yes, but it’s more difficult. Most traditional lenders require a dealer transaction. Options for private-party used utility vehicle financing include:
- LightStream (unsecured loan)
- Credit unions (may accept a signed bill of sale)
- Peer-to-peer lenders (Prosper, Upstart)
Expect higher rates and a 30–40% down payment requirement.
2. What credit score is needed for used utility vehicle financing?
Minimum: 550–600 with specialty lenders.
Recommended: 650+ for reasonable rates.
Best: 700+ for single-digit APRs.
If your score is low, consider a co-signer or a secured loan using other equipment as collateral.
3. How old can a used UTV be to qualify for financing?
Most lenders cap at 10 years old from the current model year. Some agricultural credit associations will go to 12–15 years for well-maintained diesel UTVs (e.g., Kubota RTV-X900).
4. Do I need a down payment for used UTV financing?
Almost always, yes. For used utility vehicles:
- Dealer-financed: 10–20% down
- Bank/CU loan: 15–25% down
- Zero-down options: Only for new UTVs or borrowers with 720+ credit
5. Can I finance attachments (plow, sprayer, enclosure) with the UTV?
Yes, if you purchase from a dealer. Ask for “total equipment financing,” which bundles the used UTV, attachments, and even delivery fees into one loan. Standalone accessory financing after purchase is harder.
6. What documents do I need to apply?
Typical requirements for used utility vehicle financing:
- Driver’s license
- Proof of insurance (comprehensive & collision)
- Last 2 months of bank statements
- 2 years of tax returns (for business-use loans)
- VIN and photos of the used UTV
7. Is used UTV financing tax-deductible?
If you use the vehicle more than 50% for business (e.g., farm, ranch, construction), you may deduct interest payments as a business expense. Personal-use UTV loans are not tax-deductible.
8. What’s the difference between a UTV loan and an ATV loan?
UTVs (side-by-sides) are heavier and often commercial-rated, so lenders may offer longer terms (up to 72 months) and lower rates than ATV loans. Always specify “utility vehicle” not “recreational ATV” on your application.