Kubota RTV Financing Options for Used Buyers
Table of Contents
- Quick Answer: Kubota RTV Financing Options at a Glance
- Why Used Kubota RTV Buyers Choose to Finance
- Kubota RTV Financing Options for Used Buyers
- Financing Options Compared (Table)
- What Lenders Look For
- How to Get Approved: Step-by-Step
- What a Payment Might Look Like
- Tips to Lower Your Costs
- Mistakes to Avoid
- How to Find the Right Used Kubota RTV
- Frequently Asked Questions
- Final Thoughts and Next Step
Kubota RTV Financing Options for Used Buyers
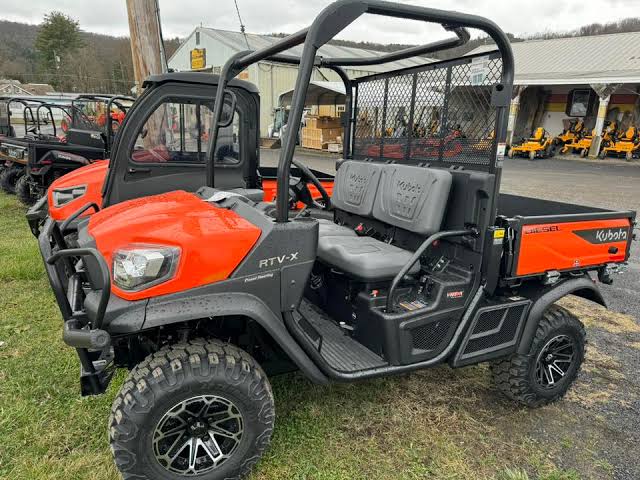
If you’ve spent any time around farms, ranches, hunting land, or job sites, you already know why Kubota RTVs have such a loyal following. They’re tough, they’re diesel-powered, and they keep working long after other machines have worn out. That reputation is also why buying used makes so much sense. A well-kept pre-owned Kubota gives you most of the capability at a much friendlier price.Kubota RTV Financing Options for Used Buyers
But “friendlier” doesn’t always mean “pay in cash.” Most buyers want to spread the cost out. The good news is that Kubota RTV financing options for used buyers are broader than many people expect. The catch is that financing a used machine works a little differently from financing a brand-new one, and knowing those differences can save you real money.Kubota RTV Financing Options for Used Buyers
This guide walks through every realistic path, what each one costs you in time and interest, and how to get approved without headaches.
Quick Answer: Kubota RTV Financing Options at a Glance
What are the best financing options for a used Kubota RTV?
The most common ways to finance a used Kubota RTV are:
- Credit union or bank loans (often the lowest rates for qualified buyers)
- Personal loans (fast and flexible, but rates vary widely)
- Powersports or equipment lenders (built for vehicles like UTVs)
- Dealer-arranged financing (convenient, with lender availability depending on the seller)
- Home equity or farm credit loans (low rates, but your property is the collateral)
- Saving and paying cash (no interest, and often the cheapest route overall)
Which is usually best? For most used buyers with decent credit, a credit union or equipment lender offers the best balance of rate and simplicity. Always compare at least three offers before signing.Kubota RTV Financing Options for Used Buyers
Why Used Kubota RTV Buyers Choose to Finance
Let’s be honest about the appeal. A used Kubota RTV can still cost as much as a decent used car, and for many people it’s a working tool, not a toy. Financing makes sense when:
- You need the machine now, such as for planting, hay season, or a property project, and can’t wait to save up.
- You’d rather keep cash on hand for fuel, feed, repairs, or emergencies.
- You’re running a small business and want to match the payments to the income the machine helps you earn.
- You want a newer, lower-hour unit than your cash budget would allow.
Financing isn’t automatically smart or foolish. It’s a tool. The goal is to use it so the monthly payment fits comfortably into your life.Kubota RTV Financing Options for Used Buyers
Kubota RTV Financing Options for Used Buyers
1. Credit Union Loans
Credit unions are member-owned, and that structure often translates into lower rates and more flexible underwriting than big banks. Many have dedicated powersports, recreational vehicle, or “other vehicle” loan products that cover used UTVs.Kubota RTV Financing Options for Used Buyers
Why buyers like it:
- Competitive rates, especially if you already bank there
- Willingness to look at your whole financial picture, not just a score
- Friendly terms and fewer surprise fees
Watch out for: Membership requirements, and some credit unions limit the age or mileage of vehicles they’ll finance.
2. Bank Loans
Traditional banks can finance used utility vehicles too, particularly if you’re an existing customer with a solid history.
Secured vs. Unsecured Bank Loans
- Secured loans use the RTV as collateral. They typically carry lower rates because the bank can repossess the machine if you stop paying.
- Unsecured loans don’t require collateral, but they usually cost more and may have lower borrowing limits.Kubota RTV Financing Options for Used Buyers
For a used Kubota RTV, a secured loan is usually the better deal.
3. Powersports and Equipment Lenders
Some lenders specialize in financing UTVs, ATVs, side-by-sides, and compact equipment. They understand what these machines are worth and how they hold value, which can make approval easier for used units.Kubota RTV Financing Options for Used Buyers
Pros:
- Familiar with used utility vehicle values
- Often quick approvals, sometimes within a day
- May finance older or higher-hour machines that a bank would hesitate on
Cons:
- Rates can run higher than a credit union’s, especially with fair or limited credit
4. Dealer-Arranged Financing
Many used vehicle sellers work with lending partners and can help you apply right at the point of sale. It’s convenient, because you can choose a machine and start the paperwork in one place.Kubota RTV Financing Options for Used Buyers
Tip: Convenience shouldn’t replace comparison. Get a pre-approval from your own bank or credit union first, then see whether the seller’s lender can beat it. That gives you real negotiating power.
5. Personal Loans
A personal loan can come from an online lender, bank, or credit union and isn’t tied to the vehicle. That flexibility is helpful if the RTV is older, or if you’re buying from a private seller who can’t accept a lender’s lien paperwork easily.Kubota RTV Financing Options for Used Buyers
Pros: Fast funding, flexible use, no collateral required.
Cons: Rates are often higher than secured vehicle loans, and terms may be shorter, which raises the monthly payment.
6. Home Equity or Farm Credit Financing
If you own land or a home with equity, a home equity loan or line of credit may offer some of the lowest interest rates around. Farm credit associations may also offer programs for agricultural equipment and vehicles.
Important: Your property secures the loan. If something goes wrong, you risk more than the RTV. Use this route only if you’re confident in your repayment plan.
7. Save and Pay Cash (or a Hybrid)
It doesn’t sound exciting, but paying cash, or putting down a very large down payment and financing the balance, eliminates or shrinks interest costs. Used Kubota RTVs hold their value well, so a larger upfront investment often feels less risky than with other machines.Kubota RTV Financing Options for Used Buyers
Financing Options Compared
| Financing Option | Typical Speed | Rate Potential | Best For | Main Drawback |
|---|---|---|---|---|
| Credit union loan | 1–3 days | Often lowest | Buyers with good credit and a local credit union | Membership required |
| Bank loan | 1–5 days | Competitive for existing customers | Buyers with established banking history | Stricter vehicle age limits |
| Powersports/equipment lender | Same day–3 days | Moderate to higher | Used or older RTVs, mixed credit | Rates can run higher |
| Dealer-arranged financing | Same day | Varies by lender | Convenience seekers | Can cost more if you don’t compare |
| Personal loan | Same day–2 days | Moderate to high | Private-party purchases | Higher rates, shorter terms |
| Home equity / farm credit | 1–4 weeks | Often very low | Landowners, farm buyers | Property is collateral |
| Cash / large down payment | Immediate | No interest | Disciplined savers | Ties up your cash |
Rates and timelines vary by lender, credit profile, and market conditions. Treat this table as a comparison guide, not a quote.
What Lenders Look For When You Finance a Used Kubota RTV
Lenders are really asking one question: “How likely is this person to repay us?” These are the factors they weigh.Kubota RTV Financing Options for Used Buyers
Credit Score and History
A higher score usually means a lower rate and easier approval. If your score is on the lower side, a larger down payment, a co-signer, or a shorter loan can offset the risk.
Income and Debt-to-Income Ratio
Lenders compare your monthly debts to your income. Lower is better. A healthy ratio signals that a new payment won’t stretch you too thin.Kubota RTV Financing Options for Used Buyers
Down Payment
Putting money down reduces the loan amount and shows commitment. For used machines, many lenders like to see a meaningful down payment, often 10% to 20%, though requirements vary.
Age, Hours, and Condition of the RTV
This is where used buying differs from new. Lenders consider the machine’s age, hours, and overall condition. Newer, lower-hour units are generally easier to finance and may qualify for longer terms. Older or high-hour machines may come with shorter terms or higher rates.Kubota RTV Financing Options for Used Buyers
Why Documentation Matters
Having a clear title, a bill of sale, and ideally service records helps the lender verify value. Missing paperwork can slow or stop an approval.
How to Get Approved: Step-by-Step
Step 1: Check Your Credit First
Pull your credit report and look for errors. Fixing a mistake before applying can improve your offers.Kubota RTV Financing Options for Used Buyers
Step 2: Set Your Real Budget
Decide what monthly payment fits comfortably, then add the costs people forget: insurance, fuel, maintenance, registration, and accessories.
Step 3: Get Pre-Approved
Pre-approval tells you your spending ceiling and shows sellers you’re serious. Apply with two or three lenders within a short window, since multiple inquiries for the same type of loan are typically treated as one when rate shopping.Kubota RTV Financing Options for Used Buyers
Step 4: Choose the Machine
Now you can shop with confidence. If you’re ready to look at what’s available, start with our used Kubota RTV for sale listings and compare models, hours, and prices.
Step 5: Inspect Before You Sign
Check the engine, hydraulics (dump bed), drivetrain, tires, and any signs of heavy abuse. A lender may require details about the machine, so have the VIN and hour meter reading ready.Kubota RTV Financing Options for Used Buyers
Step 6: Compare Final Offers
Look at the APR, loan term, fees, and any prepayment penalty, not just the monthly payment.
Step 7: Close and Insure
Finalize the paperwork and arrange insurance, since lenders typically require coverage on financed vehicles.
What a Payment Might Look Like
Here’s a simple illustration. These numbers are examples only, using an 8% APR on a $15,000 loan, and are not a lender quote.
| Loan Term | Approx. Monthly Payment | Approx. Total Interest |
|---|---|---|
| 36 months | $470 | $1,930 |
| 60 months | $304 | $3,250 |
| 72 months | $263 | $3,930 |
Notice the trade-off. A longer term lowers the monthly payment but increases the total interest you pay. If a 10% down payment reduced that loan to $13,500, the 60-month payment would drop to roughly $274.
The Takeaway
Choose the shortest term you can comfortably afford. A used RTV is a durable machine, but you don’t want to still be paying for it long after the newness wears off.
Tips to Lower Your Financing Costs
Make a Bigger Down Payment
Every extra dollar down reduces both your payment and your interest.
Improve Your Credit Before You Apply
Even a few weeks of paying down balances can nudge your score upward.
Consider a Co-Signer
A co-signer with strong credit can help you qualify or secure a better rate. Just remember they’re taking on real responsibility.
Shop Lenders, Not Just Machines
Rate differences between lenders can add up to hundreds of dollars over the life of the loan.
Ask About Prepayment Terms
You want the freedom to pay extra or pay it off early without penalty.
Time Your Purchase
Some sellers are more flexible near the end of the month or in slower seasons. Negotiating the price down also lowers the amount you need to finance.
Common Mistakes to Avoid
Focusing only on the monthly payment. A low payment stretched over a very long term can cost far more in the end.
Skipping the inspection. Financing a machine with hidden problems is a double loss, because you’ll still owe money while paying for repairs.
Forgetting the extras. Insurance, taxes, registration, and fees can add up. Build them into your budget.
Applying everywhere at random. Spread your applications within a short window and be strategic.
Ignoring the fine print. Look for origination fees, late fees, and restrictions on vehicle use.
How to Find the Right Used Kubota RTV to Finance
Financing is only half the equation. The other half is choosing a machine worth financing. Think about how you’ll actually use it:
- Farm and ranch work: Prioritize a strong diesel engine, a reliable hydraulic dump bed, and good towing capacity.
- Property maintenance: Compact size and maneuverability matter more than top speed.
- Hunting and recreation: Look for comfortable seating, a cab or roof, and good ground clearance.
- Commercial use: Durability and documented maintenance history should top the list.
Lower hours and clear service records usually mean easier financing and better resale value later. You can compare current options in our Kubota RTV UTV inventory, or if you’re still deciding between brands and models, browse all our used utility vehicles to see what fits your budget and needs.
Frequently Asked Questions
Can I finance a used Kubota RTV?
Yes. Many credit unions, banks, powersports lenders, and online lenders finance used Kubota RTVs. Approval depends on your credit, income, down payment, and the age and condition of the machine.
What credit score do I need to finance a used Kubota RTV?
There’s no single cutoff. Higher scores generally unlock better rates, but buyers with fair or limited credit can often still qualify through specialty lenders, with a larger down payment or a co-signer.
How much down payment is needed for a used RTV?
Lenders vary, but many prefer 10% to 20%. A larger down payment improves your odds of approval and lowers your total cost.
What loan term is typical for a used Kubota RTV?
Terms commonly range from about 24 to 72 months, depending on the lender and the machine’s age and hours. Older units often get shorter terms.
Is it better to finance through a dealer or my own bank?
Neither is automatically better. Get a pre-approval from your bank or credit union, then compare it with any financing offered at the point of sale. Choose whichever gives the lower overall cost.
Can I finance a used RTV from a private seller?
Often yes, but the process differs. A personal loan or a lender that supports private-party vehicle purchases is usually the simplest path. Make sure the title is clean and transfers properly.
Does financing a used RTV affect my credit?
Applying causes a small, temporary dip from the credit inquiry. Making on-time payments can help build your credit over time, while missed payments can hurt it.
Are there tax benefits to financing an RTV used for work?
Possibly. Farm and business owners may be eligible for certain deductions on equipment used for business. Rules vary, so talk to a qualified tax professional before assuming anything.
Can I pay off my RTV loan early?
Many loans allow it, but some charge a prepayment penalty. Ask about this before you sign.
What should I check before financing a used Kubota RTV?
Verify the title, hour meter, service history, and mechanical condition. Check the engine, drivetrain, hydraulics, and tires. If possible, have a mechanic look it over.
Final Thoughts
Financing a used Kubota RTV doesn’t have to be complicated. The best approach is simple: know your budget, get pre-approved, compare multiple lenders, choose the shortest term you can handle, and pick a machine with solid hours and documentation. Do those things, and you’ll end up with a tough, dependable workhorse and a payment that doesn’t keep you up at night.
Ready to find your next machine? Start by exploring our current Kubota RTV for sale, or shop our full used utility vehicle selection to compare options. Found one you like? Get in touch and we’ll help you take the next step.